Bharti Airtel: Initiation of Coverage
India's best telecom franchise, close to a fair price. Valued part by part, initiated 8 Oct 2026
- Domain
- Equities
- Kind
- Independent equity research
- Length
- 15 pp · 0.6 MB
What it found
- HOLD · Rs 1,946
- 12-month target, 6.2% above the 7 Oct 2026 price
- Rs 1,338
- DCF by part, 27.0% below the price
- 7.8%
- expected total return, including the FY27 dividend
Bear, 30%
Rs 1,709
Price, 7 Oct 2026
Rs 1,833
Target, 12 months
Rs 1,946
Bull, 27%
Rs 2,209
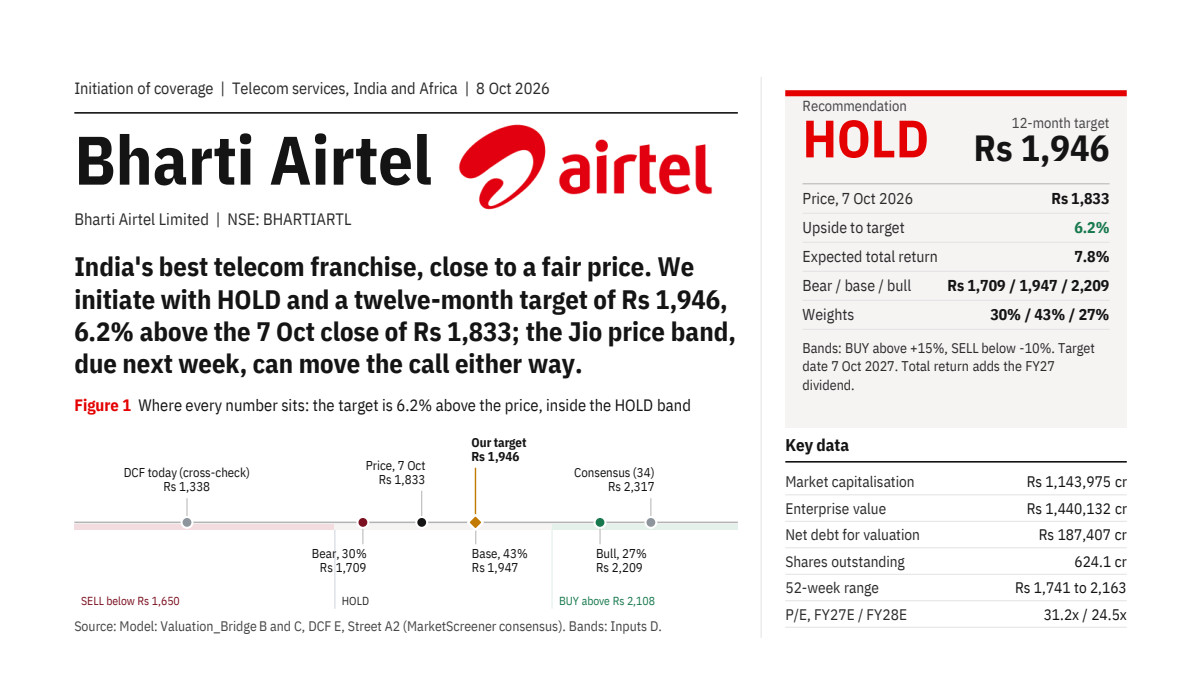
The three outcomes for 7 Oct 2027 against the price, in rupees a share. Each is a multiple of India EBIT tied to a dated event. Weighted, they give the target, 6.2% above the price and inside the HOLD band of -10% to +15%; the base case of Rs 1,947 sits on the target and is left off.
Source: Finding 4 and the metrics above; the report's Figure 1
DCF by part, today
Rs 1,338
Target, 12 months
Rs 1,946
Consensus, 34 analysts
Rs 2,317
Three answers to what a share is worth. The DCF by part, at an India WACC of 9.96%, sits 27.0% below the price and the street sits above it. The gap to the DCF is a view on the cost of capital rather than on the forecast, which is why the target weights dated outcomes instead.
Source: Metrics above and finding 5; consensus from MarketScreener, 34 analysts, 6 Oct 2026
Overview
A sell-side style initiation on Bharti Airtel, valued part by part: India mobile, Airtel Africa (79.11% owned), Indus Towers and Bharti Hexacom. The franchise leads Indian telecom on price per customer, margin and returns, but at Rs 1,833 the market already prices India ARPU growth of 9.5% a year to FY31, against 5.7% in the forecast. Three dated outcomes, weighted 30% / 43% / 27%, give a 12-month target of Rs 1,946, 6.2% above the price and inside the HOLD band. Written in the style of the CFA Institute Research Challenge; not an entry, not reviewed by CFA Institute, and not investment advice.
Findings
India mobile is the best franchise in the market. ARPU of Rs 263.9 a month is 22% above Jio's, and in FY26 the segment earned a 60.2% EBITDA margin and 18.7% after tax on its net segment assets, against an India WACC of 9.96%
The price needs more tariff repair than the forecast allows. Run through the model, Rs 1,833 requires India ARPU to grow 9.5% a year to FY31, the equivalent of 1.1 more tariff steps the size of July 2024's. The forecast already includes one repair, 5% in FY28 and 3% in FY29, and grows ARPU 5.7% a year; management guides to 4% or 5% from mix
The rule that changes the call is printed in advance. A Jio Platforms price band midpoint above US$147 bn makes Bharti a BUY; one below US$121 bn takes the target to Rs 1,720, still a HOLD. The Q1 FY28 results, due by 14 Aug 2027, are the second dated test
HOLD holds across the weights. Bear is Rs 1,709 at 30%, base Rs 1,947 at 43%, bull Rs 2,209 at 27%. SELL is out of reach at any pair of weights, and BUY needs a bull weight of 61% with no bear
The gap to the street is the multiple, not the forecast. Consensus from 34 analysts is a Buy at Rs 2,317. FY28E EBITDA sits close to Motilal Oswal's, the only full public forecast, and EPS 8.0% below it